
15 September 2026
Last week, UK investors closely monitored macroeconomic signals while looking ahead to the Bank of England's (“BoE”) forthcoming monetary policy meeting, where expectations remain firm that the base rate will be held at 3.75%. The pressure on central bank decision makers remains intense as the domestic inflation picture continues to present a challenge. Headline Consumer Price Index (“CPI”) inflation reached 2.9% in July, and market participants are awaiting Wednesday's August figures to gauge whether price pressures are broadening. However, domestic economic fundamentals provided a welcome boost at the end of the week, with UK gross domestic product (“GDP”) data outperforming forecasts and indicating resilience in business activity. This positive surprise buoyed overall market sentiment, further supported by perceived political stability under Prime Minister Andy Burnham, whose strong public approval ratings continue to reassure international investors.
Within UK equity markets, energy sector equities recorded substantial gains as escalating pipeline disruptions and supply concerns in the Middle East pushed Brent crude benchmarks past the $100 per barrel mark. Reflecting this broader shift toward energy and resource weightings, the FTSE quarterly index review triggered significant reshuffling among UK corporates: airline operator easyJet and North Sea exploration firm Ithaca Energy earned promotion to the flagship FTSE 100 following robust operational performance and trading updates. Conversely, residential developer Persimmon and gaming operator Entain were relegated to the FTSE 250, underscoring the ongoing strain that elevated borrowing costs and cautious consumer discretionary spending are imposing on domestic focused sectors.
Across the Atlantic, US financial markets worked to digest incoming inflation figures alongside persistent geopolitical instability. The US CPI registered a seasonally adjusted 0.4% month-on-month increase in August, elevating the 12-month headline inflation rate to 3.4%, while core CPI, which strips out volatile food and energy costs, edged up to 2.4% annually. Amplifying these inflationary headwinds were heightened tensions in the Middle East and ongoing conflicts involving Iran, which heightened concerns over global supply chain disruptions. Investor anxiety was further compounded by policy uncertainty surrounding President Donald Trump's renewed economic sanctions and pressure initiatives targeted at Tehran, which continue to create uncertainty across foreign exchange and commodity markets.
The compounding impacts of spiking oil prices and sticky consumer inflation sparked aggressive repricing across US fixed income markets. The yield on 2-year US Treasury notes spiked to 4.62%, its highest level in two years, as interest rate futures rapidly priced in an approximate 70% probability of a rate hike by the Federal Reserve (“Fed”) at its upcoming policy gathering. Surging government bond yields placed considerable downward pressure on equity valuations, causing major benchmark indices to struggle throughout most of the trading session. The S&P 500, Dow Jones Industrial Average and Nasdaq Composite suffered four consecutive days of declines before recovering slightly to stage a modest rally on Friday, as fund managers adjusted their portfolio allocations to account for higher borrowing costs over a prolonged horizon.
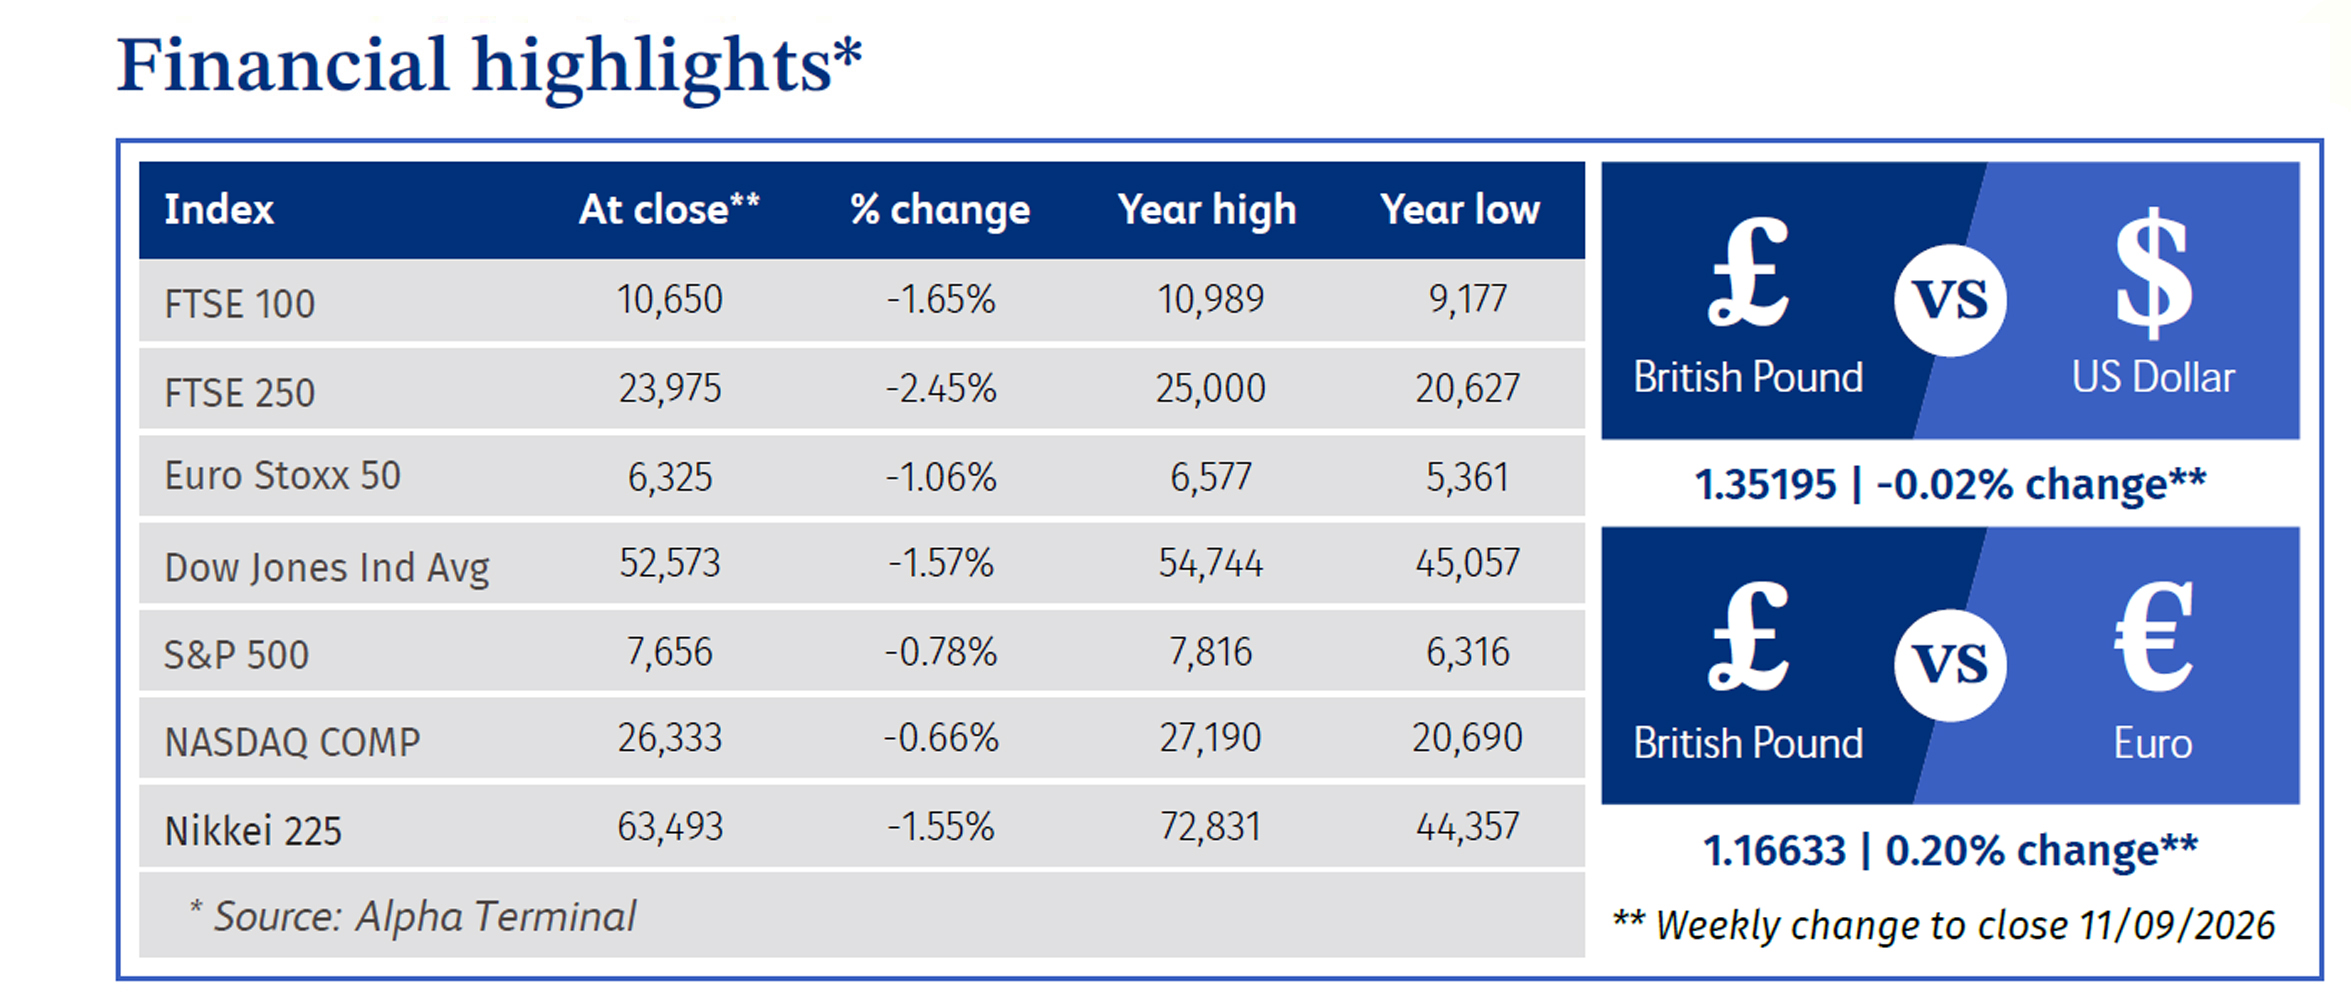
BP is a leading British multinational energy company with a vast portfolio spanning oil and gas exploration, production, refining and a growing renewable energy business. Over the week, the company's shares listed in London climbed 4.61% to close at 564.6p on Friday. This solid performance was primarily driven by a strong macroeconomic rally in global crude oil prices, which bolstered the outlook for the energy giant's operating margins. The stock's momentum was further amplified by a significant analyst upgrade from Goldman Sachs, which raised its price target to 700p.
Sage Group is a leading UK based multinational enterprise software company that provides accounting, HR and payroll solutions primarily for small and medium-sized businesses. The company's shares fell 8.89%, ending the week at 958p, driven by a broader sector sell off and investor reaction to a major debt refinancing manoeuvre. During the week, Sage listed a new €500 million bond, carrying a 4.2805% interest rate (maturing March 2032) to early redeem its older €500 million 3.820% notes (due February 2028) ahead of schedule, planned to be on 28th September 2026. Caught in wider macroeconomic headwinds and lacking a positive operational catalyst, the stock slid as the market focused on the increase in debt servicing costs.
Associated British Foods (“ABF”) is a diversified British multinational food processing and retailing company that operates the global fashion retailer Primark alongside major sugar, grocery, agriculture and ingredients businesses. The company's shares fell 11% to end the week at 1,843.5p per share, after a disappointing trading update revealed significant challenges across two of its core divisions. The sell off was driven by a 3% decline in Primark’s fourth quarter (“Q4”) sales amid weak European demand. Additionally, management warned that sugar losses could be between £70 million and £170 million in 2027 due to low sugar prices, high gas costs and a poor UK beet crop.
Market Commentary prepared by Walker Crips Investment Management Limited.
This publication is intended to be Walker Crips Investment Management's own commentary on markets. It is not investment research and should not be construed as an offer or solicitation to buy, sell or trade in any of the investments, sectors or asset classes mentioned. The value of any investment and the income arising from it is not guaranteed and can fall as well as rise, so that you may not get back the amount you originally invested. Past performance is not a reliable indicator of future results. Movements in exchange rates can have an adverse effect on the value, price or income of any non-sterling denominated investment. Nothing in this document constitutes advice to undertake a transaction, and if you require professional advice you should contact your financial adviser or your usual contact at Walker Crips. Walker Crips Investment Management Limited is authorised and regulated by the Financial Conduct Authority (FRN:226344) and is a member of the London Stock Exchange. Registered office: 128 Queen Victoria Street, London, EC4V 4BJ. Registered in England and Wales number 4774117.

Important Note
No news or research content is a recommendation to deal. It is important to remember that the value of investments and the income from them can go down as well as up, so you could get back less than you invest. If you have any doubts about the suitability of any investment for your circumstances, you should contact your financial advisor.

The value of investments can fall as well as rise. Investors may get back less than invested. Past performance is not a reliable indicator of future results.
The value of investments can fall as well as rise. Investors may get back less than invested.


