

6 October 2026
The UK economy grew faster than first thought in the second quarter of 2026, with UK gross domestic product ("GDP") revised up to 0.5% from 0.4% by the Office for National Statistics (“ONS”), with the services sector doing most of the work. The manufacturing Purchasing Managers' Index ("PMI"), a survey of how manufacturers themselves see conditions, edged up to 51.9 in September from 51.7, holding above the 50 mark that separates growth from contraction. Households looked less comfortable with Nationwide reporting annual house price growth halved to 0.8% in September from 1.6%, the weakest since December 2025. The 10-year gilt yield was little changed at 5.37%, keeping borrowing costs in focus ahead of the budget in three weeks’ time.
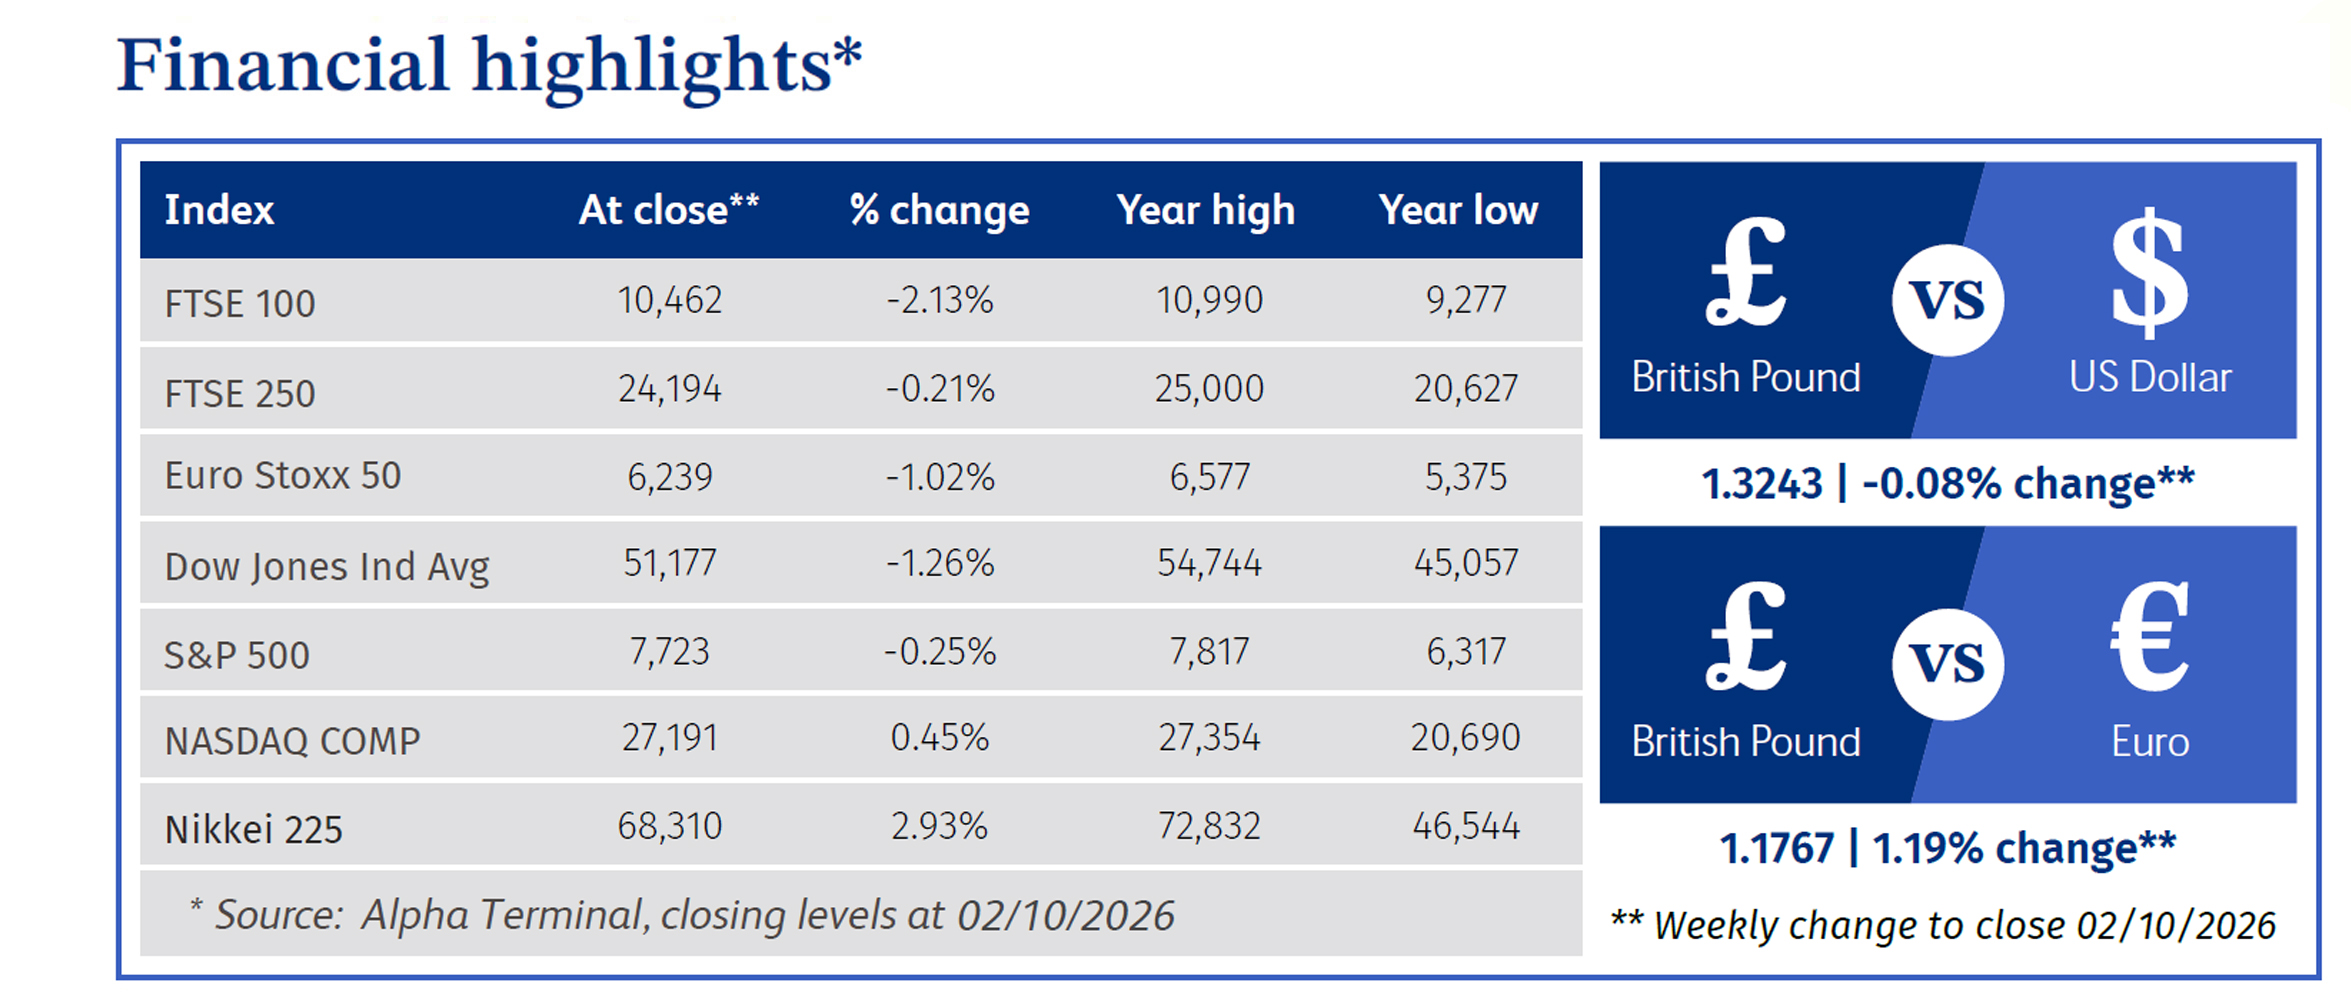
Oil set the direction for UK equities. Brent crude moved above $108 a barrel early in the week as hopes faded for progress in talks between the US and Iran, then eased as flows through the Strait of Hormuz improved. In UK markets, the FTSE 100 index fell further than the FTSE 250. That split is consistent with the larger index carrying more energy and overseas earners, so a reversal in crude is felt there first. Company news ran against the macro picture in places: bakery chain Greggs raised its outlook while flagging job cuts, and pharmaceuticals group AstraZeneca filed a new cancer drug application in the US.
Across the Atlantic the labour market and prices pointed different ways. The economy added 29,000 jobs in September against expectations of roughly 90,000, with July and August revised down by a combined 60,000 and unemployment up to 4.2%, lowering the implied chance of a Federal Reserve interest rate rise in October. Inflation pulled the other way, the personal consumption expenditures price index holding at 3.4% for the year to August and the core measure at 3%, while the Institute for Supply Management's prices index jumped 6.8 points to 77.9. That tension explains the week's apparent contradiction: 2-year yields fell after Friday's payrolls release, yet the 10-year Treasury ended nine basis points higher at 5.27%. The S&P 500 slipped while the Nasdaq Composite rose.
European inflation surprised upward and sovereign risk returned to France. Eurozone annual inflation accelerated to 3.8% in September from 3.2%, ahead of the 3.6% expected, with Spain at 4.9% and Italy at 4.1%, reinforcing the case for the European Central Bank to keep policy restrictive. France presented a 2027 budget targeting a deficit of 5% of GDP, but doubt over whether a divided parliament will pass it pushed French borrowing costs sharply higher. The 10-year German Bund yield moved the other way, falling 14 basis points to 3.46%, which is what a shift towards the bloc's safest debt looks like.
Japanese equities rose, the gains concentrated in artificial intelligence (“AI”) and semiconductor shares rather than spread across the market, so the Nikkei 225 climbed while the broader TOPIX was little changed. The Bank of Japan's summary of opinions showed members divided on how fast to tighten further, tempering expectations of an October interest rate rise and leaving the 10-year government bond yield broadly unchanged at 3.08%. Tokyo core inflation accelerated to 2.7% for the year to September from 1.8%. China announced its largest stimulus package since 2024, including mortgage interest subsidies for first time buyers, and its official manufacturing PMI returned to expansion at 50.1, but equities fell as investors judged the measures insufficient.
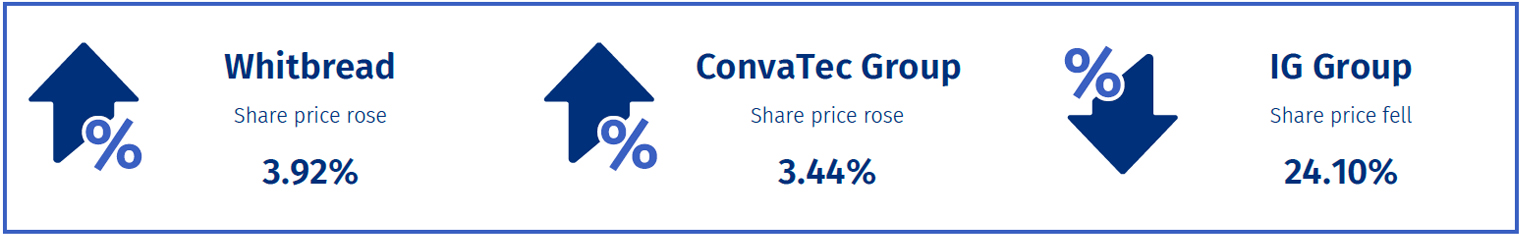
Whitbread is the UK's largest hospitality group, operating hotels across the country under its prominent Premier Inn and Beefeater brands. Over the past week, the company's shares listed in London climbed 3.92% to close at £24.40 on Friday. This solid performance was primarily driven by a strong network expansion that beat market expectations. The move showcased a 292-room addition. The stock's upward momentum was further amplified by management's fast track conversion strategy and a broader UK hospitality sector upgrade from sector analysts.
ConvaTec Group is a leading UK based global medical products and technologies company that discovers, develops and commercialises therapies for chronic conditions, primarily in advanced wound, ostomy, continence and infusion care. The company's shares rose 3.44%, ending the week at £21.66, driven by a new product launch, active share buyback execution and positive margin guidance. During the week, ConvaTec announced the launch of its Cure Aqua hydrophilic catheter across the US and Canada, expanding its continence care portfolio. Concurrently, the firm advanced its $200 million share buyback programme while reiterating forecasts for materially higher second half profit margins in infusion care.
IG Group Holdings, a global leader in online trading and investment services, experienced a 24.1% decline in its stock price this past week, closing at 990p. The drop was largely driven by a massive investor sell off on Friday following a disappointing third quarter (“Q3”) trading update. After sluggish broader market conditions, the company slashed its full year revenue growth forecast from 15% down to mid-single digits and reported that Q3 revenue is expected to fall by 14% year-on-year to roughly £240 million. Management noted lower over-the-counter revenue retention, prompting City brokers to downgrade forecasts as expected margins dropped below 45%.
Market Commentary prepared by Walker Crips Investment Management Limited.
This publication is intended to be Walker Crips Investment Management's own commentary on markets. It is not investment research and should not be construed as an offer or solicitation to buy, sell or trade in any of the investments, sectors or asset classes mentioned. The value of any investment and the income arising from it is not guaranteed and can fall as well as rise, so that you may not get back the amount you originally invested. Past performance is not a reliable indicator of future results. Movements in exchange rates can have an adverse effect on the value, price or income of any non-sterling denominated investment. Nothing in this document constitutes advice to undertake a transaction, and if you require professional advice you should contact your financial adviser or your usual contact at Walker Crips. Walker Crips Investment Management Limited is authorised and regulated by the Financial Conduct Authority (FRN:226344) and is a member of the London Stock Exchange. Registered office: 128 Queen Victoria Street, London, EC4V 4BJ. Registered in England and Wales number 4774117.

.jpg "Market Commentary Podcast: Deep dive on Structured products")
Important Note
No news or research content is a recommendation to deal. It is important to remember that the value of investments and the income from them can go down as well as up, so you could get back less than you invest. If you have any doubts about the suitability of any investment for your circumstances, you should contact your financial advisor.

The value of investments can fall as well as rise. Investors may get back less than invested. Past performance is not a reliable indicator of future results.
The value of investments can fall as well as rise. Investors may get back less than invested.


